Explain the difference between perfect competition in the short-run and the long-run
Perfect competition consists of infinite buyers and sellers, homogenous products, perfect information, and no barriers to entry and exit. Each firm is a price-taker so they each face a perfectly elastic average revenue (AR) curve. This means that marginal revenue is also constant. Firms aim to maximise profits, so they produce at the point where marginal costs = marginal revenue (MC=MR). This means that firms can make supernormal profit in the short run, as shown by the shaded rectangle op1c1q1.
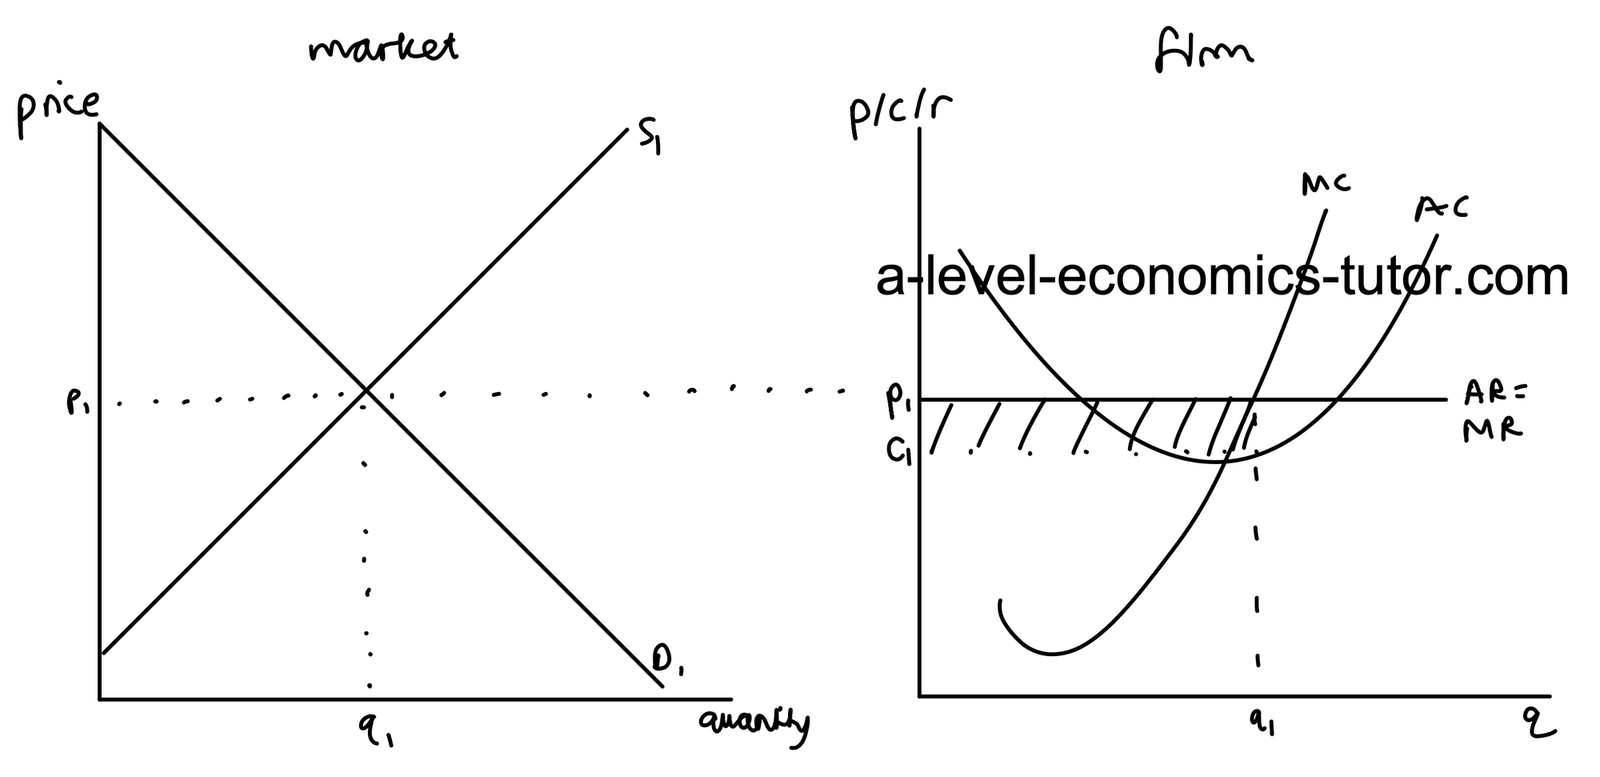
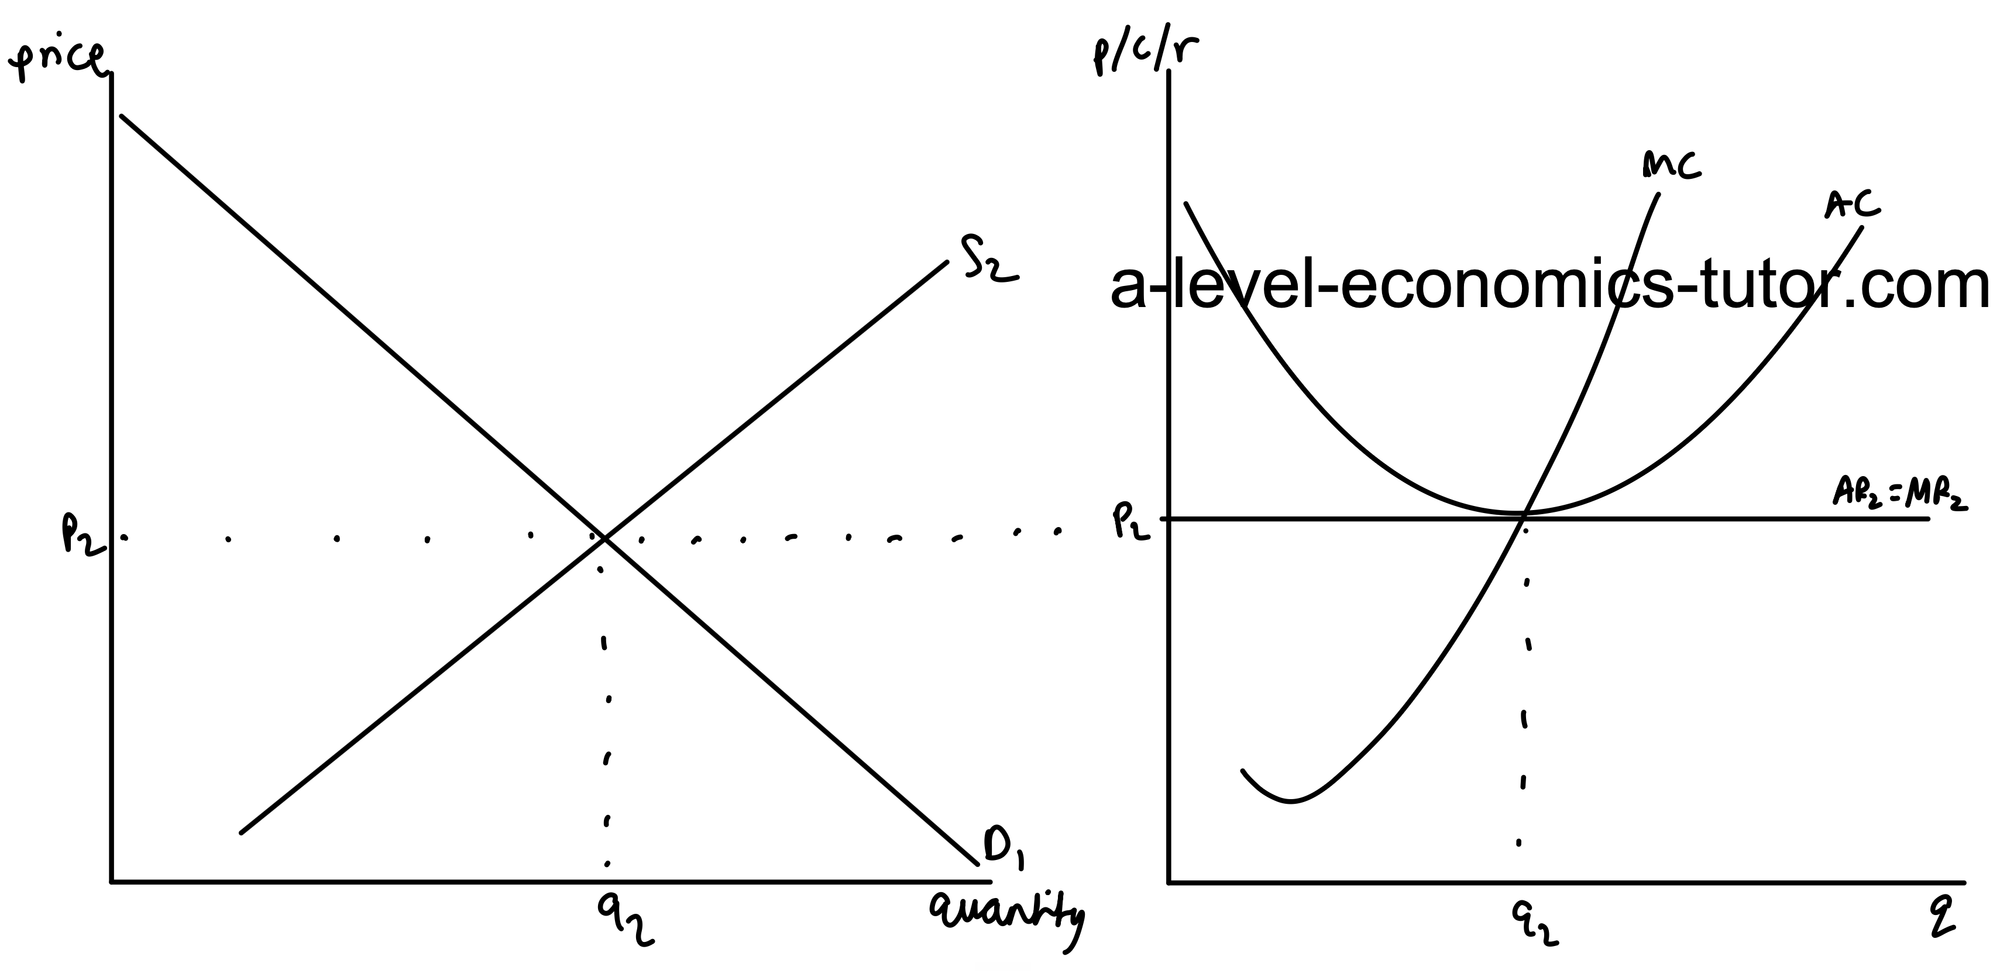
Since there are no barriers to entry, profit-maximising firms would be easily able to enter the market. They are incentivised to do so because they know that existing firms are making profit in excess of normal profits, meaning firms are able to at least cover the cost and the opportunity cost of entering the market. As a result of new firms entering the market, market supply increases. Therefore, each firms’ average revenue falls as they have to accept a lower market price. This eventually leads to a new long-run profit maximising equilibrium where existing firms are only able to make normal profit.
A-Level Economics Tutoring
I offer one-to-one and small group A-Level Economics tutoring for students across the UK and internationally. With 87+ five-star Google reviews and tutoring experience since 2017, I specialise in helping students understand difficult concepts and improve their exam technique.